$STRC Catalyst Posts
June 13, 2026Single-day social intelligence recap and verified catalyst posts · ← Back to $STRC Profile · Market Rankings
💬 Curated Viral Posts & Community Evidence
9 source posts analyzed· 2026-06-13T14:07:07+00:00My conversation with @scottmelker on @YahooFinance on @Strategy , the largest holder of Bitcoin in the world, why $GOOG and $MSTR use preferred equity, paying $STRC dividends, buying and selling $BTC , and $MSTR performance. [Spoken audio]: There may be no more hotly debated company on Wall Street right now than strategy. They hold 845,000 Bitcoin, about 4% of all that will exist and have an entire capital stack around it. To bulls it's genius, but the skeptics are out in droves. We're going to get the truth straight from the horse's mouth from Fongly, the president and CEO. Let's go. What is up, everybody? Welcome to The Daily Wolf on Yahoo Finance. I'm your host, Scott Melker, also known as the wolf of all streets. And we've only got 15 minutes. So I'm going to go ahead and bring on Fong Lee right now. Fong, how are you doing? Welcome to the show. I'm doing great, Scott. Thanks for having me. So I'm glad that we got this rare opportunity to speak. We obviously don't often do interviews and guests here, but I figured this was the best opportunity to get the truth straight from the horse's mouth. So I want to start with the 845,000 Bitcoin you hold, which is roughly 4% of all of the Bitcoin that will ever exist. I mean, to put that in perspective for people, where does that rank against other companies, funds, even countries? Well, there was a point in time when we and IBIT were pretty close. And IBIT seen quite a bit of outflows in the last 30 days or so. So, we are now by far enlarged the largest corporate and now the largest holder, identified holder of Bitcoin in the world. And we plan to stay that way. Okay. So you've obviously created an entire preferred stack, you STRC, STRF, STRK, STRD. Seems that this is the new focus of the company to some degree. And I spoke very candidly about that with Michael at Vegas Money 2020. What is digital credit to you and why are traditional fixed-come investors and other retail investors buying it? Well, the advantages of digital credit to us, the company strategy, there's advantages of digital credit to the purchasers, and there's advantages of digital credit to Bitcoin. To us, the company, we want to be able to raise capital that is non-dilutive, that also does not have maturity and duration risk, and preferred capital is actually perfect for that. I'll give you an example, there's more recently, Google last week raised $80 billion of capital and a large portion of that used preferred capital, in that case convertible. And when you have, you want to invest into something that has a long duration that is uncertain what the return profiles are, is it one year, two years, three years, four years, i.e. AI, preferred capital is actually perfect for that. So if you now take that analogy of what does AI look like, high capital investment, right, the underlying is something everybody believes in, but the return profile is uncertain, that's what Bitcoin is, right? So for us, strategy, preferred capital, in this case, perpetual preferred, is perfect for a Bitcoin investment, unlike convertible bonds that have have a maturity of anywhere between three and eight years. And even better than capital as equity, which is immediately diluted to us. So that's why it's good for us. Why is it good for somebody who, an investor, right? Where else can you get something that is an 11.5% tax deferred, cash paid, dividend yield? Used to be monthly, now it's twice a month, right? And on top of that, have something that's significantly over collateralized in our particular case, four to five times X over stretch. It doesn't exist out there. Too good to be true. In this particular case, no, I don't think it's too good to be true. The only challenge with the product, maybe it's 10 years old or 10 months old, needs some maturity and to prove itself over time. And it's a fairly low volatility product. So that's the second piece. The third, why is it good for Bitcoin? There's a lot of debate for this. Ultimately, as much as I like to believe, everybody fully understands the bull case for Bitcoin, and everybody wants a non-sovereign, decentralized, store value asset. When I go to a cocktail party in Washington, DC, nine out of 10 people look at me when I say I'm a Bitcoin person, as if I'm having either a political conversation or it's too complicated for them, right? And those nine out of 10 people should have access to Bitcoin. They have a right to have access to Bitcoin. And they're not gonna do it by opening up Coinbase account, they're certainly not going to do it with a self-custody solution. They're not going to do it even through iBit. They're definitely not going to do it through MSTR. Those people should be on board the Bitcoin. Everybody should be happy with that as an outcome if you're a Bitcoiner. I totally agree. So on the Q1 earnings call, you alluded to using the full range of capital tools, and that included the discipline sale of Bitcoin. And I think, you know, Sailor famously said that he would use a small sale of Bitcoin to inoculate the market, right? You said you were going to do it weeks before you did it. You sold a simply 32 Bitcoin, a very small amount, which obviously was bought back in a much greater size immediately. But you planned it, but the, I guess, naysayers are saying that it was a forced sale that indicates that you will continue to be a forced seller. So how do you dispel that myth? We said we're going to do it, right? We have $52 billion worth of Bitcoin on our balance sheet, at some point in time, we have to put it to work. And to put it to work, one option is to sell it. And so we sold less than 1% of 1% of our Bitcoin. And we thought $2.5 billion or $2.5 million, 32 Bitcoin was a reasonable amount. Why did we do it? One, to inoculate the market. What does that mean is to indicate to all classes of shareholders and stakeholders a strategy that we're willing to sell our Bitcoin, right? Two, to test our processes. And three, to give ourselves the opportunity for future tax loss harvesting. It's really that simple. We did not sell it because we needed to sell it to meet our cash dividend obligations of $100.5 million. If we did, we would have sold a lot more than two and a half million, right? And so there's talk out there. They did it to satisfy their dividend. Now, we didn't do to satisfy our dividend. We did it to want to inoculate the market, to test our processes, and three, be able to capture future tax losses. That's the reason. I mean, isn't satisfying the dividend like $1.6 billion a year or something? You sold 32 bitcoin. Yeah, it's $1.7 billion a year. We sold 32 bitcoin. By the way, $1.7 billion a year sounds big to most people, right? Our equity, which is primarily how we satisfy our dividends, trades about $2.7 billion a day, right? So it would take about four hours of full selling into the market of our equity, right? Obviously, we didn't wouldn't do enough for our one, but that's four hours of a day of trading volume to satisfy our $1.7 billion cash dividends. So it's really not, you know, I don't, I don't lose sleep at night wondering how are we going to pay our dividends? So that's, that's like, so really low on the list of risks to the company. Right. And you've still built a USD reserve up that at one point gave years of dividend coverage. And I think the same critics are screaming loudly because you closed one of those convertible notes and that cash reserve went down, even though you raised another 100 million this week. So is this something you're doing to batten down the hatches? Is this a signal to the market? Do you need a cash reserve or is it just something that the market's demanding? I mean, why the cash reserve? Yeah. So first, why the cash reserve? Mathematically, I do not believe I need a cash reserve for the reasons you mentioned. Now, from a risk perspective and to satisfy those sort of four different stakeholders are common, our preferred, our Bitcoin and our debt holders, especially our debt holders, right, and our shareholders, they feel that it's less risky to have a cash reserve, right? Like, what if Bitcoin was to crash by 90%, we would have two and a half years or whatever it is, right? So we took the 2.25 billion down to north of 700 million. Why did we do it? Because at that point in time, that was the best way to buy back our converts of $1.5 billion. Well, look, we've also said we're going to bring it right back up, right? And we've done it $100 million dollars at a time so far last week, right? And by the way, we also bought a hundred million dollars of Bitcoin last week right after we sold two and a half million. Nobody talks about the purchase of a million, a hundred million. They talked about the sale of two and a half, but we'll bring the cash reserve back up and refresh it over time because it satisfies our debt holders and our stretch holders. The criticism there has been that this one week's action has been dilutive to strategy shareholders. But if you obviously zoom out over any meaningful period of time, that number has only gone up. So how do you address that? Every year, since the beginning. And look, we take week to week actions, but we think strategically year to year. And really long-term, we think in four or five year time horizons, right? And so are we increasing Bitcoin per share every single year? the answer is yes. The best year was 2024. We increased it 77 percent. Last year we increased it 30, 23 percent. This year or year today we've increased 12 percent. And we went from 13 percent down to 12 percent. And so there will be weeks that we're going to be taking actions that reduce Bitcoin per share and weeks that we increase. Big question is every single year are you increasing? If you look at the capital outlays of a company, that's why you have capital investment is an operating expense. If you look at a cash flow of a highly capital-intensive company, you'll have weeks and months where the cash flow dips, weeks and months where it increases. But the question is, over the course of the year, are your cash flow positive? And really, for them, maybe you're making a capital investment that's $500 million in one year, and you see returns of $1.5 billion over three years. That would be accretive. Now, we're talking about a week to week, you know, and we choose to disclose this week to week. We don't have to. Yeah. That is a voluntary disclosure. What we have to do is disclose quarter to quarter. And with the weekly disclosure and the greater transparency, we get more scrutiny. And I think over time, hopefully more maturity from all of our constituents. And so just to keep running down the list of things I keep hearing, obviously SDRC is trading below par, which prefs do, and they're designed to be able to. So for people who don't, I guess, live in this space, what is that signal and what is it not? What does it mean when something is trading below par and what happens if it's not immediately back to 100? So it's an equity, first of all. It is a preferred equity. It's not debt, and it's definitely not a money market, even though some people are using it in place of a money market. It's definitely not that. And so although it's designed to trade within in a tight window of power, 99 to 101, there'll be times when it doesn't. I'll give you an interesting stat, total shareholder return. Bitcoin, from October when it started decreasing to now, is down 50%. That's the TSR of Bitcoin. The TSR of stretch during that time, up 4%. So even though stretch is now trading whatever today at 96 cents on the dollar, that means it's down 4% during that period, but when you take the 11 and a half percent dividend that's paid over the last 10 months, that's up 8%. So if you're a shareholder of stretch over that period of time, you're up 4%, right? It is designed to have Bitcoin as the underlying and to have stable, fairly stable price and to give you return 11 and a half percent over the course of the year. I would argue it's done basically that. And if I told you in October, I'm gonna design an instrument with Bitcoin as the underlying. Bitcoin is gonna go down 50%. I'm gonna give you a 4% TSR. Would you believe me? No. Yeah. Well, we've done it, right? And so now last couple of weeks, it's gone down because Bitcoin has gone down, but it'll come back up, right? We have the mechanisms to do so. We could increase the dividend, right? As an example, we could shore up the US dollar reserve if that's what's important to people. I have a strong belief, one, will continue to pay the dividends, and two, it'll trade back in part. Wish we had more than two minutes left, so I'm going to ask you the good one for the soundbite. What would it take for you to actually be a four-seller of Bitcoin, which is what the critics keep screaming about? And then, I guess, as a corollary, what are people just completely getting wrong that you're seeing in the narrative? The most realistic scenario of us being a four-seller of Bitcoin is we have about three and a half billion dollars of prefers that come due to 2028, right, with a high strike price, over $400. If at that point in time, but Bitcoin has lost a significant amount of its value, our share price is depressed. We would sell the Bitcoin, potentially, to satisfy the converts. Now, that's a, I'll call it an edge case because we can also just refinance those converts. We could equitize them. Right? That's, you know, we're talking 20, 28, we're talking two years out. I don't see any scenario until then that we become a four seller of Bitcoin. And even then we have other opportunities and options. And if you're a believer in Bitcoin, which I am, right, Bitcoin is not going to go down significantly between now and then we're about to enter another bull cycle. I agree. So we got about 45 seconds. What's the one thing people are just totally getting wrong in the narrative? I think big picture, zoom out. We've been doing this for six years. We've outperformed Bitcoin by 50% in the last six years, right? And so if you believe in Bitcoin, we are amplified Bitcoin. Bitcoin's been up 37%. We've been up north of 40, closer to 50% during that period of time. We've outperformed every company in the Mag7 except for NVIDIA. Incredible, right. Incredible. Fong, thank you so much for coming on and giving us the information straight. We deeply appreciate it and we'll all be watching closely. Everybody else will see you back on Monday.
· 2026-06-13T21:42:06+00:00saturn credit hit $205m TVL in 10 weeks. 127% growth in 30 days. $100m deployed through pendle in under a month. impressive until you look at what's underneath. 45% of USDat backing is STRC, a perpetual preferred equity instrument collateralized by one company's BTC holdings.
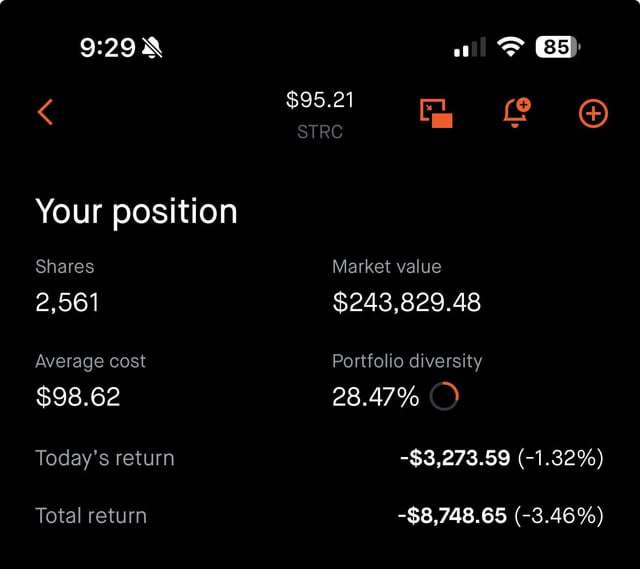
· 2026-06-13T01:34:46.467000+00:00Added more STRC now $243k deep. Suggested for you
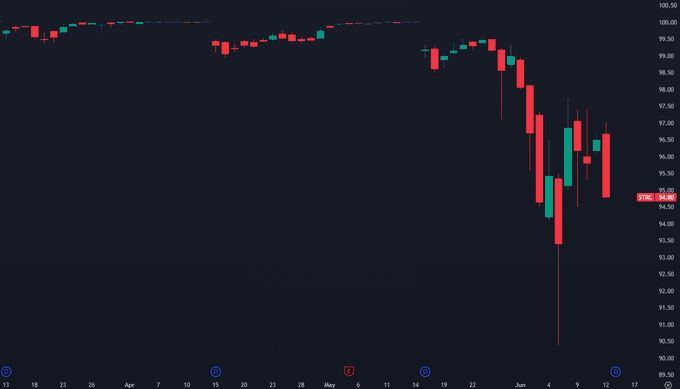
· 2026-06-13T05:30:37+00:00MicroStrategy's $STRC has performed poorly this month due to BTC's drag. Current price is $94.8, and it's estimated that the interest rate hike trigger will kick in around early July. There's a chance it could return to around $100 by July. This potential repair opportunity

· 2026-06-13T10:35:00+00:00Matt Cole: “Bitcoin is down over 50% from its high, yet both $SATA and $STRC have delivered positive total returns during the bear market.” Reduced volatility. Income. Positive returns while Bitcoin bleeds. “That is success, in my view.”
· 2026-06-13T17:54:27+00:00$STRC dividend is only 11.5% BTW
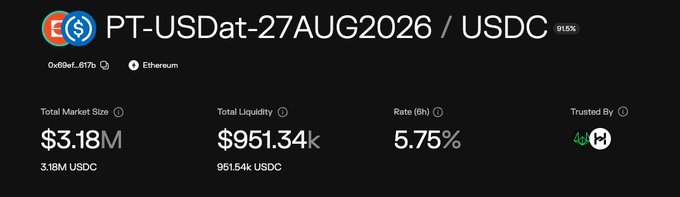
· 2026-06-13T11:24:23+00:00Saturn's PT-USDat looping lending pool has received liquidity support from @wintermute_t , and currently there's nearly $1M in liquidity available for borrowing *USDat-related products are not affected by $STRC fluctuations Below is the PT-USDat looping guide provided by Intern
· 2026-06-13T05:07:10+00:00Strategy's $STRC closed at $94.8 on Friday, marking a complete dividend cycle without returning to par. Saylor stated that Strategy will not issue STRC when it is not at/above par, so this means they have been unable to raise capital for $BTC purchases via STRC since May 15th.
· 2026-06-13T17:00:08+00:00That's the problem. Three definitions of the word Yield. 1. BTC Yield as defined by Strategy is an increase in Bitcoin Per Share. 2. $STRC pays a fiat Yield of 11.50 APR funded from selling $MSTR . 3. Typical Yield on a stock is paid by income statement cash flow.
