$ASST Catalyst Posts
May 30, 2026Single-day social intelligence recap and verified catalyst posts · ← Back to $ASST Profile · Market Rankings
💬 Curated Viral Posts & Community Evidence
13 source posts analyzed· 2026-05-30T03:39:57+00:00MY CURRENT PORTFOLIO 60% BTC 30% MSTR 3% ASST 1% MTPLF 6% CASH NOT FINANCIAL ADVICE
· 2026-05-30T16:36:04+00:00NOW IS THE TIME @Strive $ASST can ease Senior Claims up to the 50% level from 35% or so here (I prefer 60%), making ASST the most explosively degenerate asymmetric geyser that will rip the whole head off when BTC starts its race to $250K. Meanwhile, a DIP to $65K BTC only
· 2026-05-30T22:12:27+00:00ASST from $17 to $793. From May 1st to May 22, the company has reported $150 million deployed into Bitcoin. Let's assume they raise even less. Let's go with $100m per month with SATA issuance. $100M/month preferred issuance buying BTC, 13% preferred cost, dividends paid via
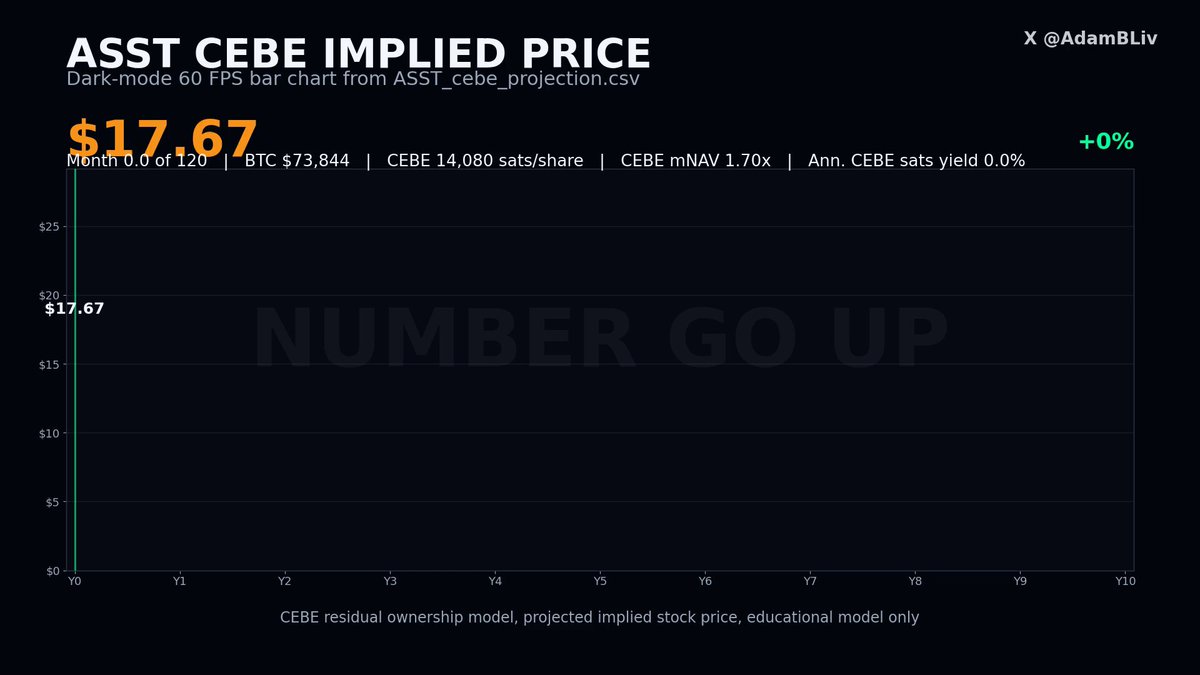
AI visual analysis: The image displays a bar chart depicting the price of Bitcoin over two months. The chart shows the price decreasing from $17,687 in May to $746 in June. The x-axis represents the months, with May labeled as the initial month of June labeled as the final month of May. The y-axis shows the change in price per cent, ranging from -4% to 4%. There is text above and below the chart explaining what it shows: "ASST from $17 to $793. From May 1st to May 22nd, the company has deployed $150 million into Bitcoin. Let'S assume they raise even less. Let'S go with $100m per month. $100M/month preferred issuance buying BTC, 13% preferred cost. $100M/Month paid via".
· 2026-05-30T14:02:00+00:00JUST IN: Strive $ASST CEO Matt Cole ( @ColeMacro ) just said, "The digital credit market can easily reach $3 trillion in the next 10 years, as demand grows exponentially." "Digital credit is a massive opportunity. There’s strong demand for more issuers." [Spoken audio]: And so, you know, I think as other players enter the digital credit ecosystem in the Bitcoin Treasury landscape, I think the market will reward that to the extent that they can get liquidity in the digital credit instrument, and so that's going to be providing something that the market wants. So that could be a digital credit that pays in the pound, it could be the one that pays in the Euro, in the yen, and obviously there's different regulations. But just at a high level, if you think about I think about digital credit as it's obviously not a money market account That's literally like the first thing you see on our website but I do think that digital credit it designed well, it can be better than a money market account and That the demand for that can be Exponentially high. I think it's gonna be north of three trillion dollars pretty easily in the next 10 years And when you think about something that is that large of an opportunity opportunity. It makes sense for there to be more than one issuer. Right now there's two. I think it makes sense for it to be much more than two. And for each issuer to really think about what is the value proposition that I'm bringing that's different than the ones that are out there. And I think that there's so many different ways that that could go. It could be what you pay in. For Strive, we took the approach of being kind of the perpetual Bitcoin bull, we're going to run fast with high amplification, and we're going to pay a higher yield on the digital credit ecosystem. And we think that there was going to be demand on both sides and that thesis is playing out. But I think there's a lot of other very coherent thesis is that I think we'll have a lot of demand with a digital credit instrument that will power a Bitcoin Treasury company. So you know, it's going to be very interesting to see what the different players come up with. But I think there's a lot of demand for more players. And we want to be helpful in getting more players out there because it obviously it helps us to have a thriving digital credit ecosystem to having a thriving Bitcoin Treasury ecosystem. And I think that's what we're going to see over time.
AI visual analysis: In this image, there is an interview-like format with a man sitting at a desk while talking into a microphone during a video call. The main subject of the discussion is the digital credit market and its potential growth over the next decade. The man's statement suggests that demand for digital credit will reach $3 trillion within the next ten years, highlighting the significant impact this industry could have on the economy. As more issuers enter the market, the availability of financial services online could lead to a widespread adoption of digital currency among consumers and businesses alike.
· 2026-05-30T13:00:09+00:00This will speed up dramatically from here!!! #Bitcoin $ASST $SATA

AI visual analysis: The image features a man wearing a suit, smiling for the camera while standing next to stacks of money. The background includes an orange circle with a white "B" inside, which appears to be a Bitcoin logo or symbol. The caption below the image reads "This will speed up dramatically from here!!! #Bitcoin $ASST $SATA". This suggests that the man is promoting Bitcoin and its potential benefits in terms of efficiency and value.
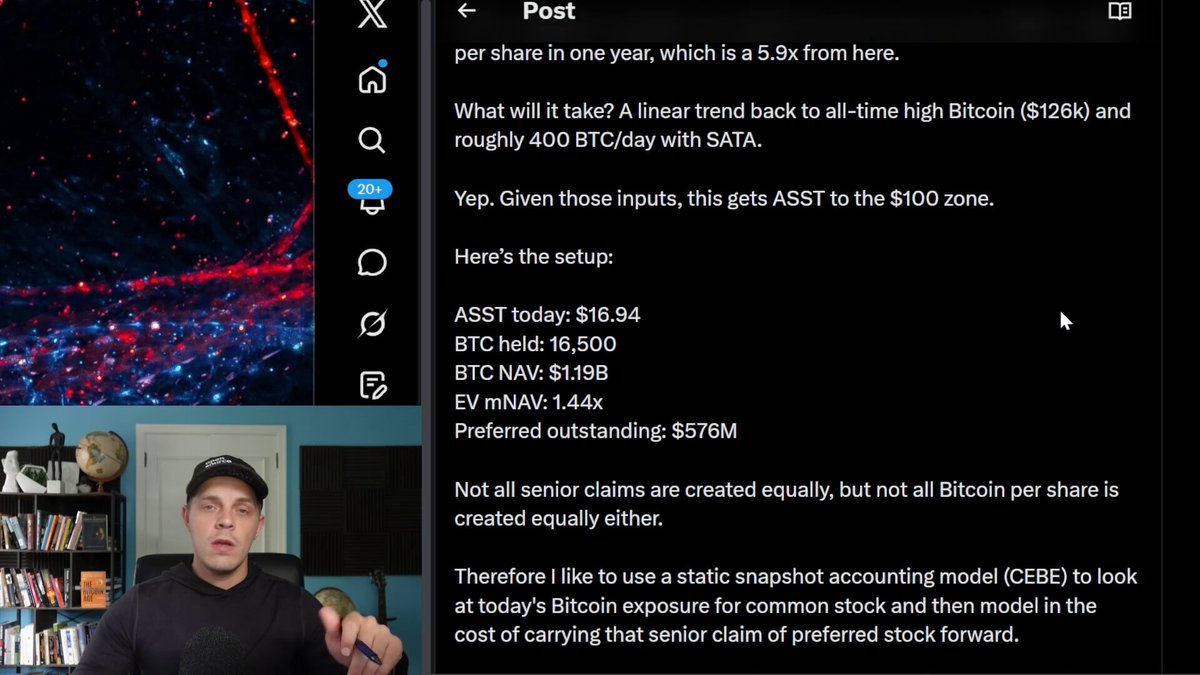
· 2026-05-30T21:56:23+00:00I fully believe ASST is going to $100 in short order. Here I use the CEBE framework to totally declaw the Strive bear case and project out what the daily SATA dividends are going to do for ASST shareholders: [Spoken audio]: So what am I projecting? All I'm doing is projecting a linear trend back to Bitcoin's all-time high, 126,000. If you don't think it's going to happen in one year, like this model, that's just fine. Maybe you think that it takes longer than a year. Maybe you think they can buy more Bitcoin than this input here. Maybe you think they can buy less. I don't know. These are just guesses. these are some estimates that I'm putting into a model. It's not my opinion. I'm just trying to mathematically gauge out when we could see a $100 share price for ASST. So this is the setup today. When I ran the math this morning, ASST was $16.94. So that was, you know, toward the lower end of today's trading price. But obviously they hold $16,500 Bitcoin at least Just as of today, the Bitcoin nav just under $1.2 billion a Bitcoin, the enterprise value MNav is a 1.44X, but I don't like that number, we're going to talk about why. But the preferred outstanding is $576 million. Now you guys know that I've been using the CEBE model on this channel and on my X account to do a lot of stock price projections and the dialogue in the Bitcoin Treasury investor community. starting to develop a little bit and we are seeing some friendly debate about this particular metric. And in my opinion, this is how I see things. Obviously, you can tell me if you disagree or not, would love to have that conversation with you if you leave a comment, but this is the way that I see the capital structure and I see how I could calculate the stock price going forward using a snapshot measurement mechanism that is CB or CEBE, Common Equity Bitcoin Exposure. My good friends at True North were actually debating this metric and they talked about it on the hurdle rate recently too, where they were discussing, what do senior claims mean? What does it mean to have a senior claim on the Bitcoin? And this is where I wanna be very clear. I don't think all senior claims are converted equal because obviously debt that is coming due, maybe you have high interest rate debt, maybe there's another company that has low interest rate debt, maybe there's a company like Strive that only has perpetual preferred equity that never comes due. Obviously, I think the market should definitely value those companies differently depending on the risks and the perceived risks of that capital structure. But in my mind, CEBE is not a valuation model necessarily. It's a static snapshot of looking at the balance sheet. Now, obviously, like I said, not all senior claims on the balance sheet are created equal, but at the end of the day, senior claims are senior claims. So I would just challenge this thinking here where I would ask any Bitcoin Treasury company investor, do you think it is possible to just look at a balance sheet and take a snapshot picture and find out what the common stockholder owns economically. Is it possible, without diving into subjectivity about what the valuation of the stock price is, in theory or in practice, could you take a static snapshot of the balance sheet and find out what you own economically? Now I don't think it's perfect to bucket all the senior claims together because I do think that they're different. Therefore, the companies out here like Strategy Strive, they are saying that they are senior and they're saying it in terms of liquidation preference. Now to be clear, I hate the liquidation preference talk as well. I absolutely hate it. I saw this happen with the strategy preferreds last year. And in my mind, this is such a hyper inefficient market that I think potentially one out of 100 preferred stock buyers could even tell you what the liquidation preferences. But at the end of the day, these are senior claims in the event of a liquidation, but then on top of that, if you look at the language and the prospectuses, it's actually different. There are differences between SATA and Stretch. Pardon me if I don't get this exactly correct, but I do think there is some terminology in the SATA prospectus where they talk about having to dilute the ASST shareholders to pay the dividends on SATA. I actually think that there's specific language around that. So obviously it's tough. It's just like how much stock do you put into the senior claim? So obviously, I think when you talk about valuing the residual, what is left over for the common shareholders when you own ASST, I think that the market is always pricing that. That's why CEBE, in my mind, isn't a valuation metric. It's just saying, yes, there are senior claims, we are going to take that to make it a percentage of the balance sheet because obviously that might tell a more accurate story than Bitcoin per share because we know that obviously if not all senior claims are created equally, then all Bitcoin per share isn't created equally either. And anybody would agree with that because there's different terms of debt that you could take on. There are different perpetual preferred equity structures that you could use. But preferred stock isn't free money, so I don't think BTC yield tells the entire story. So this is the way I think about things, okay? Sorry if I'm ranting too much, but this is the way I think about things. I think that if you just bucket the senior claims together, all of them together because the companies are the ones that are saying that these are senior claims, and then if you are trying your hardest to take a static snapshot of what you own as a common stockholder. You can then project out into the future the cost of carrying that claim. Now, obviously we know there's a cost of capital. Strive is paying out a 13% yield. So there is a different cost to carrying the senior claims. I think that what you can do is take a snapshot of the residual if you bucket the senior claims together and then I can project out what I think bitcoins price appreciation will be. I will project out how much bitcoin I think they can buy, how much common stock they can sell at a particular multiple, and also how they're going to pay the dividends. Are they going to pay it with selling common stock, with selling bitcoin, using bitcoin derivatives? I can model all of those things. So my price modeling is this. I'm taking a static snapshot of this accounting model. It's just accounting. It's not valuation. Trying to calculate today's residual and then the multiple above that residual is the valuation of how the market is pricing the stock today and then what I can do is put in the inputs and then each subsequent month I can then take another snapshot. So you're going to see what that looks like here. So what did I model? I modeled that the cost will be 13% dividends paid via common stock equity issuance so I'm modeling in them selling common stock to pay the dividends this is fantastic and it's actually going to be at the same exact CEBE multiple that the stock is trading at today because obviously you guys know if there is a higher CBM nav here obviously those are better terms you can get more bitcoin with less share dilution that way so this is why the math is bullish because this This assumes no multiple expansion, Bitcoin simply recovers linearly back to its prior all-time high over the next 12 months, so that means 126k Bitcoin by next June of 2027. And then I'm modeling in them buying 400 Bitcoin per day using only the preferred equity model but the common stock to service those dividends. So SATA is adding senior claims onto the balance sheet the entire time. But you guys know I've explained a lot of this on the channel, obviously Bitcoin rising reduces those senior claims because we know that the obligation that fixed senior claim, those are not compounding things, but the Bitcoin is compounding. So we use this word drag, the drag against the common equity. And what I would probably suggest for the CB framework here is to maybe change that word because I think drag that has a negative connotation to it. But at the end of the day, you want drag if you want an amplified bet on Bitcoin. To me, this stock run up over the last three months has been the market not only rewarding the amplification or the drag on the balance sheet. They are rewarding the possibility of continuing to add drag onto the balance sheet. So drag isn't a bad thing. Drag is a great thing given that you're a Bitcoin bull and that's why I love the CB model because it takes into account everything and it totally de-claws all of the bears. What do you see with the critique of the perpetual preferred equity model with strive or with strategy? It's always the dividend obligation. It's the cost of these preferred shares, but this puts the math into the open, totally declaws all of the clown bears out there. And I can say, actually, I'm going to take an accounting snapshot of what the preferred claims are costing the common stockholders. And obviously, when Bitcoin goes up over time, adding drag is worth it to the common stockholders. So I think there's a lot of negativity of, oh no, You actually don't have more common equity Bitcoin exposure because you're issuing the SATA shares, but obviously the math works out amazingly as long as Bitcoin continues to go up until the right. And obviously if you're buying ASST, you think that will happen anyway. So I like the CB model. I acknowledge that it's not perfect, but obviously if you are claiming that the different senior claims need to be treated differently, then you're introducing some subjectivity. You could argue that maybe you are introducing subjectivity by stacking them all together in the first place. But so far, I think it's the best simple snapshot accounting not valuation model. So obviously, using this static snapshot model every single month over the next 12 months, ASST absolutely smashes Bitcoin's performance with this model given these inputs. That's what it looks like. $19 stock after month one, 22 after month two, 26 after month three, and then all the way down to $100 per share by month 12, given Bitcoin trending linearly back to 126K in one year and buying 400 Bitcoin per day with only SATA, not issuing the common stock to buy Bitcoin, and you're paying the dividends with ASST. This is what that accounting snapshot looks like every single month going forward into the future. Now, obviously, reality is not going to unfold linearly like this. And this is a quick caveat. This is not factoring in either the common stock dilution from the warrants that are coming up. And that's not a bad thing, actually, because Strive is actually going to get a lot of working capital if the warrants are exercised. So I'm actually not including that because obviously that would be introducing in some more assumptions here. you could look at the math and see the common stock dilution. That might suck for the stock price in the short term, but depending on what the Bitcoin price is at, depending on the multiple of ASST, they could actually take that capital and greatly increase your common equity Bitcoin exposure. So that's super exciting if you're in the stock long term. But regardless, this is what the model tells you. The green is the stock price for ASST. The orange is the Bitcoin cumulative return. So that's what the outperformance looks like given those inputs. How much Bitcoin can they buy per day with the daily dividends? I don't really know, but all I know is that when I run the math, how can you not be gigabolish on this company? They are going to raise the net asset value floor so high by just continuing to accumulate the Bitcoin. And remember, this is with no multiple expansion, the market pricing the CB residual at a multiple any higher than it is today. This is just the static multiple, starting from today, extrapolated 12 months into the future. So if you actually see a 2.5x multiple over the common equity Bitcoin exposure, things are going to get absolutely ridiculous in a good way for the ASST shareholders. Anyway, that's all I have for you guys. I could not be more bullish on this company. Incredible job team. I love the stock. I love SATA. Digital credit is taking over. And I just gotta say, whoever could have seen this coming. If only there were some guy named the Bitcoin Wizard who could have told you guys about this. I'm just kidding, thank you guys so much for your support. If you could do me a favor and like the video and subscribe to the channel, that way you can continue to support me, spread the Orange Gospel of Bitcoin, digital credit, sailor, strive, whatever, to the entire masses. Thank you so much everybody, have a terrific day, do not party too hard. Class dismissed.
· 2026-05-30T17:58:59+00:00There you go. If you're mad about $MSTR and $ASST buying up all the Bitcoin, you're welcome to front run them and bid up the price.
· 2026-05-30T21:36:40+00:00$MSTR > $ASST Matt Cole = thin-skinned "ceo" Michael Saylor = Thick-Skinned Founder Saylor welcomes negativity, criticism, and lies from the news, analysts, and accounts. I've seen zero threats of lawsuits or retaliation. Saylor knows how to outmaneuver his critics and
AI visual analysis: The image features a man wearing a suit and tie with a big smile on his face, looking directly at the camera. The caption reads "$MSTR $ASST Matt Cole = thin-skinned $MSTR $ASST Michael Saylor = Thick-Skinned Founder Saylor welcomes negativity, criticism, and lies from the news, analysts, and accounts". This caption suggests that the man is a successful businessman who has faced challenges due to his thick skin.
· 2026-05-30T02:45:05+00:00WHY I AM EVEN MORE BULLISH ON STRIVE (ASST) THE CASE FOR $100 PER SHARE
· 2026-05-30T13:36:47+00:00$ASST can pay $SATA dividends for 9 years even if Bitcoin depreciates 10%/year. So, no. $ASST is not overleveraged.
· 2026-05-30T20:11:13+00:00The little wick to $99.97 getting bought up instantly is the potential to what daily dividends could look like. Every. Single. Day. $ASST has a clear growth path to being the fastest growing company in the world and it’s well deserved with what they have built.
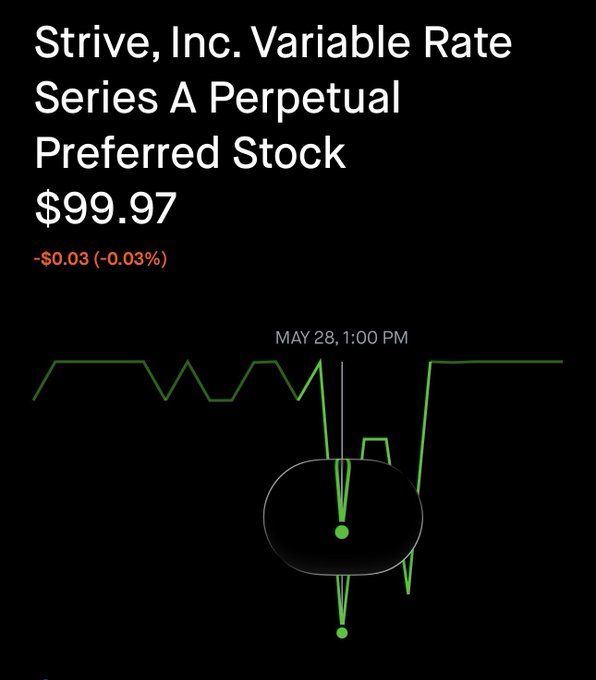
AI visual analysis: The image features a clock with an upward arrow pointing towards the number 99.97, indicating that something has been bought at this price point immediately. The text above the clock reads "The little wick to $99.97 getting bought up instantly is the potential to what daily dividends could look like". It suggests that once the price of stock has reached $99.97, the value will continue to grow rapidly and consistently over time, making it an attractive investment opportunity for those looking to accumulate long-term wealth through passive investing strategies.
· 2026-05-30T22:39:02+00:00When you buy $MSTR and $ASST , you are early adopters to the companies resetting the cost of capital for the financial system. I don’t think any other companies can come even close to providing the same amount of upside potential. The TAM is essentially unlimited.
· 2026-05-30T21:54:28+00:00I fully believe ASST is going to $100 in short order. Here I use the CEBE framework to totally declaw the Strive bear case and project out what the daily SATA dividends is going to do for ASST shareholders: