$XRP
Trending UpSnapshot Window: 2026-08-03 16:50 UTC · ← Back to Crypto Overview
Social Momentum Summary
Total Engagement - Comments: 2, Retweets: 3, Likes: 1043, Impressions: 4224
Verbatim Community Citations & Social Evidence 5 source posts analyzed
Xelon Network has reached 300K+ users in just 4 months. Get ready for migration. Xelon features are being successfully added to Xelon's app and will soon enable users to finish their migration from testnet. Stay tuned. Special reward for our loyal testnet miners: We’re
One thing I appreciate is that @quipnetwork seems focused on solving a real infrastructure challenge rather than chasing whatever narrative is trending that week That approach usually ages well
Crypto is evolving beyond narratives. At CoinEx Rising Tide, industry voices shared their views on the trends shaping the next chapter of crypto—including AI, real-world applications, infrastructure, and adoption. The future of crypto will be built on practical value, stronger
The Bank of Italy ran some tests comparing USDC vs traditional rails across 9 corridors. Verdict: "no systematic cost advantage" over traditional channels. This conclusion is wrong, because their methodology is wrong, or at least outdated. Read their cost table. The onchain
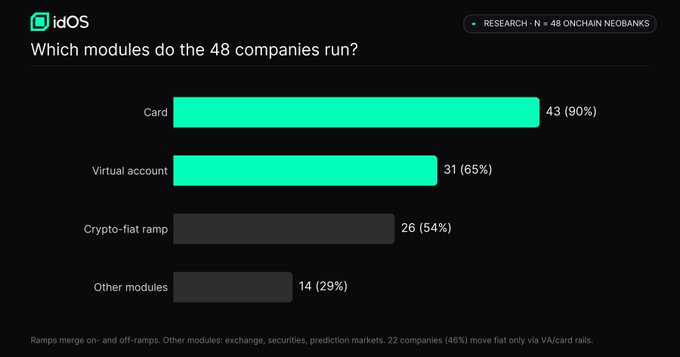
AI visual note: A bar chart titled "Which modules do the 48 companies run?" shows that among 48 onchain neobanks, 43 (90%) offer Card services, 31 (65%) offer Virtual accounts, 26 (54%) offer Crypto-fiat ramps, and 14 (29%) offer other modules like exchange, securities, and prediction markets. The image illustrates that the vast majority of onchain neobanks rely heavily on traditional rails (cards, virtual accounts), with only 54% having direct crypto-fiat ramp capability—suggesting that the Bank of Italy's comparison was flawed because most stablecoin-dependent corridors actually move money through legacy banking infrastructure rather than purely onchain.
又有说去OK