$HBAR
Trending UpSnapshot Window: 2026-07-10 12:50 UTC · ← Back to Crypto Overview
Social Momentum Summary
Total Engagement - Comments: 0, Retweets: 0, Likes: 5, Impressions: 151
Verbatim Community Citations & Social Evidence 1 source posts analyzed
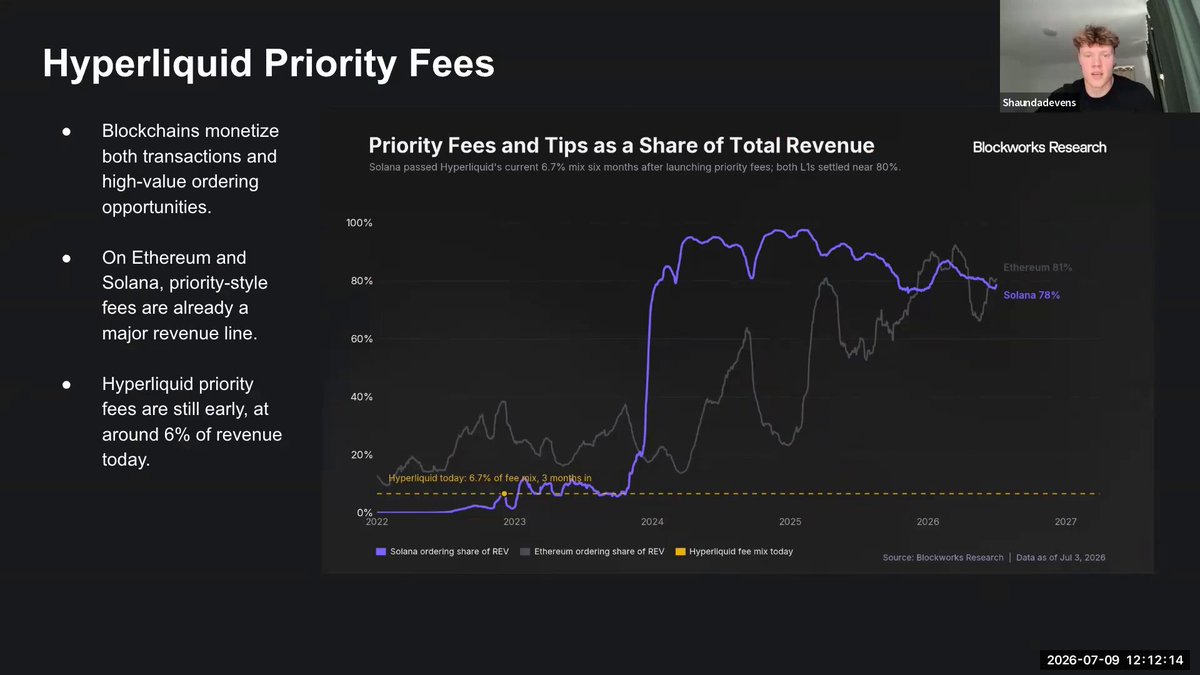
From our Monthly Analyst Hours: a quick primer on Priority Fees, including how they work, where adoption stands today, and early estimates of the upside. Comprehensive report coming soon. [Spoken audio]: So moving on I'd like to discuss hyperliquids priority fees and to contextualize blockchains monetize two sides of their demand. The first is the demand to transact which they monetize with base fees and the second is the demand for high value opportunities that the blockchain can internalize because the validators control sequencing and execution which they monetize with priority fees and because there are incredibly high value opportunities for example liquidations and arbitrage, these represent a large portion of an L1's real economic value. So Ethereum and Solana, for example, it's around 80% of their revenue in priority fees. But for Hyperliquid that only recently released these priority fees, they're still only around 6%. So it's worth looking into how exactly these fees work and how they can grow, which we'll do in the next slide. So importantly, we need to understand Hyperliquid's priority fees in the context of hypercores block ordering, which works a little bit different than other L1s. So instead of fee priority or a pure time priority, hypercore first groups the orders based on their type. So first cancels and passive orders, which remove or add liquidity into the book are processed. And only after that can aggressive flow, for example, immediate or cancel orders actually interact with it. So you can think about it that in each block first hyper liquid lets market makers update their positioning and then allows traders to interact with that liquidity. So in that context Hyperliquid added a priority fee that traders can attach to their aggressive orders which ranges from one to eight basis points on their execution notional and each basis point that they add is equivalent to around a 45 millisecond latency reduction. So this does two things. Firstly it internalizes a lot of the latency competition that would otherwise happen off-chain and be leaked in infrastructure spend, and second, it forces informed takers to eventually give back part of their returns to the protocol, similar to what we see with MEV and other chains to guarantee their execution. Alongside this, Hyperlink could also add REIT priority, which lets traders pay for earlier access to mempool data. That gives them around another 100 millisecond REIT improvement introduction. So the diagram shows how these latency improvements stacked with client-side optimizations can make for much, much faster transaction speeds. On the next slide, we'll move on to the impact that this has already had. And we noticed that adoption is still very narrow. So only 244 wallets have actually used priority fees over the last 30 days, and only around 114 daily ride users and only three daily read users. However, in terms of revenue, the interesting thing is that this revenue is actually already somewhat material, so priority fees have added $3.6 million in revenue since launch and now make up around 6% of hyperligas total revenue. And for some assets like SpaceX and other HIP3 equity markets, we're seeing that priority fees are already higher than the base fee revenue. And what we observe is that a lot of this is limited to high value opportunities, While traders are already internalizing a lot of their high-frequency trading returns with these fees. So when we look at who exactly is using these priority fees, we found that the majority were directionally neutral over time. And when we looked at the top markets and looked at the top fee-paying wallets in those markets, we found that these traders were paying around 33% of their visible returns back to the protocol via these fees. So in the next slide, we can try to extrapolate how this might look like as usage spreads. So obviously this is going to be hard to predict because unlike base fees there are a lot of assumptions like total edge, how much of that edge gets internalized and also just in general how many opportunities there are. But our mental model is that priority fee revenue is going to depend on two things. So first it's going to depend on the total edge available to takers and second how much of that edge traders are forced to give back to the protocol for execution. So when we looked at takers already using these fees, the eligible IRC orders, we saw that the total edge from targeting state liquidity on hyperliquid is around $244,000 a day. And based on that, we could make assumptions on how much of that edge can be captured as takers are actually forced to bid more for priority. And with this reconstructor range from 25 to 75% with the high end showing an extreme case where priority fees essentially become a standard latency cost that every trader is forced to use to access these opportunities. And based on this, we find that just right priority fees alone could generate around 25 to 75 million dollars in incremental revenue per year. But keep in mind that these are still preliminary estimates but the point that we're trying to make is that priority fees are still very early on used in only niche cases by very small cohort of traders but we do expect these to grow materially. We will be publishing a full report on this in the coming future along with going over the REIT side of priority fees so just stay tuned for that and with that